Medicare Part D Prescription Drug Coverage in the Hudson Valley
Prescription costs can be one of the biggest financial surprises in retirement, and choosing the wrong Part D drug plan can mean paying far more than you need to. At Health Options NY, we help residents across the Capital District, Kingston, and Saugerties sort through the options, understand their formularies, and pick coverage that actually fits their medications and budget. Our guidance is provided at no cost to you because we are compensated directly by the insurers, not by your premium.
Medicare Part D is the prescription drug coverage component of Medicare, provided through private insurance carriers. Each plan maintains a formulary, which is a list of covered drugs organized into tiers that determine how much you pay at the pharmacy. Formularies are not permanent, and are subject to annual amendments, meaning a drug that was covered this year may be placed on a different tier or removed entirely next year.
This is why reviewing your plan every fall during Open Enrollment matters, even if nothing in your health situation has changed. Our team reviews the Annual Notice of Change documents so you understand exactly what is shifting before the new plan year begins.
Not all Part D plans are built the same. Premiums, deductibles, copays, and formularies vary significantly from one carrier to the next, and the plan with the lowest monthly premium is not always the most cost-effective choice once you factor in what you actually take.
Health Options NY represents 10 organizations offering more than 20 products, which means we can run a side-by-side comparison across multiple carriers rather than steering you toward a single option. We look at your specific medications, your preferred pharmacy, and your income level, including whether IRMAA surcharges may apply, to find the plan that makes the most financial sense for your situation.
One of the most costly mistakes a new Medicare enrollee can make is delaying Part D enrollment without having creditable prescription coverage in place first. If you go without creditable drug coverage for 63 or more consecutive days after your Initial Enrollment Period, you will face a late enrollment penalty that is added permanently to your monthly premium for as long as you have Part D. That penalty does not go away.
Our team walks you through enrollment windows, confirms whether your current employer or group coverage qualifies as creditable, and makes sure you are enrolled at the right time to protect yourself from a lifelong surcharge. For high-income clients, we also review the IRMAA two-year lookback, since your 2026 Part D premium surcharge is calculated based on your 2024 Modified Adjusted Gross Income.
Prescription drug coverage is one of the most confusing parts of Medicare. Formulary changes, tier structures, coverage gaps, and annual plan terminations create a lot of noise, especially during the fall Open Enrollment season when mail piles up and phone calls from high-volume agencies seem endless.
Health Options NY operates differently. Jacquie Wolf, Susan Diamond, and Dr. Eva Turner each bring a distinct background to the table, and every consultation is one-on-one. We schedule appointments manually to make sure each client gets focused, unhurried time. Clients consistently tell us they feel much calmer after speaking with us, which is exactly the outcome we work toward.
What is a formulary and why does it change every year with Part D plans?
A formulary is the list of prescription drugs a Part D plan agrees to cover, organized into tiers that determine your out-of-pocket cost at the pharmacy. Tier one drugs are typically the least expensive, while higher tiers carry larger copays or coinsurance. Carriers are permitted to amend their formularies annually, which means a drug you rely on could be moved to a higher cost tier or removed from coverage entirely at the start of a new plan year. This is one of the primary reasons reviewing your Annual Notice of Change document each fall is so important, even if your health and prescriptions have not changed.What happens if I miss my Medicare Part D enrollment window?
If you go 63 or more consecutive days without creditable prescription drug coverage after your Initial Enrollment Period ends, Medicare imposes a late enrollment penalty. This penalty is calculated as a percentage of the national base beneficiary premium multiplied by the number of months you went without coverage, and it is added permanently to your monthly Part D premium for as long as you remain enrolled. Unlike some other financial missteps in Medicare, this penalty does not expire or reset. Confirming whether your current coverage qualifies as creditable before your enrollment window closes is one of the most important steps in the transition to Medicare.Can my Part D premium be higher because of my income?
Yes. Higher-income Medicare beneficiaries pay an Income-Related Monthly Adjustment Amount, known as IRMAA, on top of their standard Part D premium. The surcharge is calculated using a two-year lookback on your Modified Adjusted Gross Income, so your 2026 Part D costs are based on your 2024 tax return. For 2026, individual filers with income above approximately $109,000 and joint filers above approximately $218,000 will pay an IRMAA surcharge. If your income has dropped significantly since that reference year due to retirement or another life-changing event, you may be able to appeal the surcharge using Form SSA-44.Does my employer health plan count as creditable coverage for Part D?
It depends on the specific plan. Creditable coverage means your employer drug coverage is at least as good as the standard Medicare Part D benefit. Most large group employer plans meet this standard, but not all do. Your employer or plan administrator is required to notify you each year whether your coverage is creditable. If you are unsure, it is worth confirming before your Initial Enrollment Period closes, because relying on non-creditable coverage can trigger a late enrollment penalty once you eventually do enroll in Part D.Does working with a Medicare broker for Part D cost me anything?
It does not cost you anything. Health Options NY is compensated directly by the insurance carriers, not by your premium or out-of-pocket costs. This means you receive personalized plan comparison, enrollment guidance, and ongoing annual review support without paying a fee for the service. The no-cost model is a core part of how the agency operates, and it applies to all Medicare services, including Part D plan selection and review.How often should I review my Part D plan, and when is the best time to do it?
You should review your Part D plan every year during the Medicare Annual Enrollment Period, which runs from October 15 through December 7. During this window, you can switch plans, and any change you make takes effect on January 1 of the following year. The best time to start that review is in early fall, once you receive your Annual Notice of Change document from your current carrier. This document outlines any formulary changes, premium adjustments, or network updates taking effect in the new year, giving you the information you need to decide whether to stay or switch.What is the difference between a standalone Part D plan and drug coverage through Medicare Advantage?
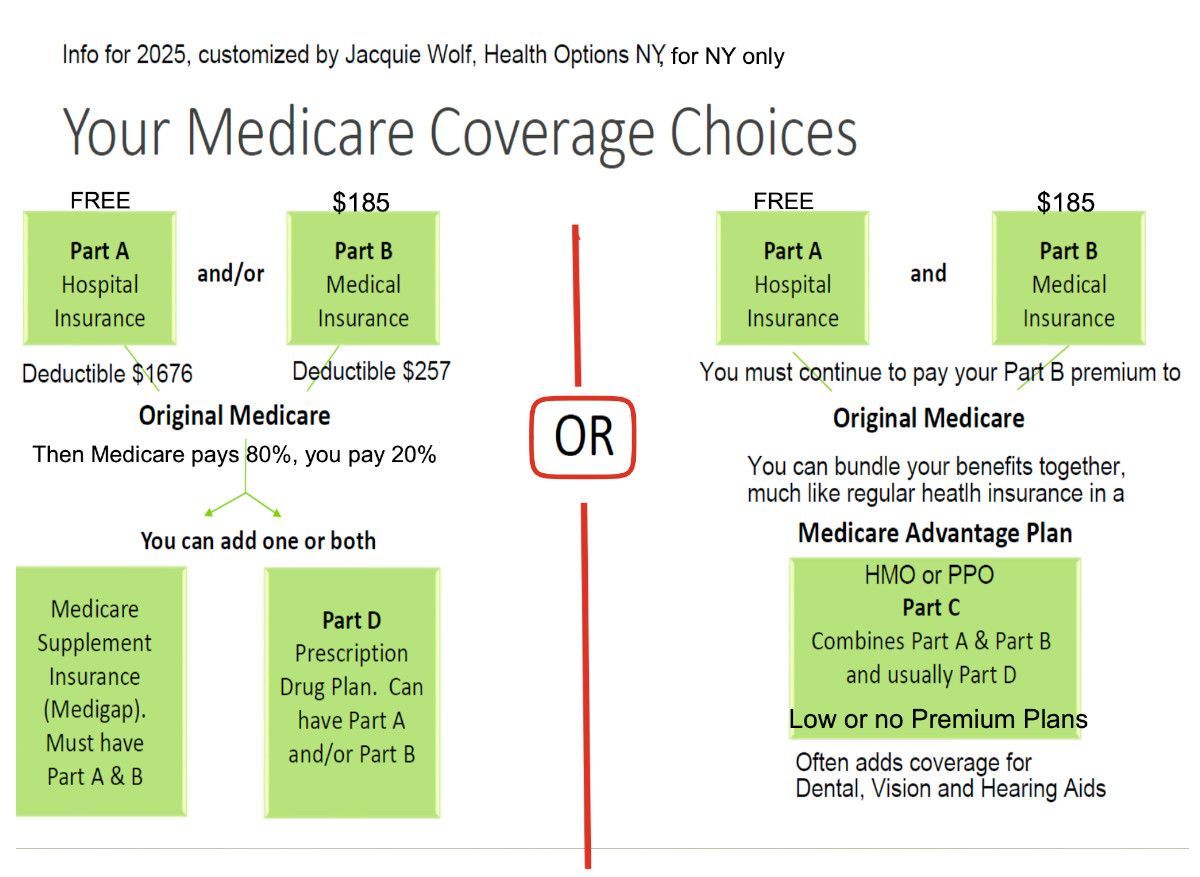
A standalone Part D plan is purchased separately and works alongside Original Medicare, which includes Parts A and B. Medicare Advantage plans, also known as Part C, often bundle prescription drug coverage directly into the plan, so you would not need a separate Part D policy. However, Medicare Advantage plans are annual contracts subject to network restrictions and yearly changes, while standalone Part D plans pair with Original Medicare and any Medigap supplement you carry. In New York, Medigap plans are considered lifetime contracts with no lookback period, which makes the standalone Part D plus Medigap combination a popular choice for many residents.
REVIEWS
At Health Options NY, we simplify Medicare navigation. Our team helps you avoid pitfalls and offers support. If we made your journey easier, please leave a review!
Trusted by the Saugerties Community
Our Saugerties team is committed to making Medicare guidance simple, personal, and easy to understand. If our support has made a difference for you, please consider sharing your experience with a review.
Jacquie Wolf is the best health plan advisor. She knows we ant the best coverage at the most affordable costs. Jacquie feels like a family friend.
- Kathleen Kourie
Health Options NY made selecting the right medicare plan for me and my husband easy. They navigated through all the confusion and answered all our questions and ultimately found the right plan for us.
- Caren Belcastro
Jacquie got on the phone with me and not only helped me sign up for Medicare but, by asking me a series of questions, determined which advantage plans would cover my current physicians and prescriptions.
- Nancy Tierney
Jacquie at Health Options NY has been my go-to health insurance resource and advisor for many years. With her help, knowledge and expertise, navigating this complex and confusing process has become stress-free for me.
- Katie Doty
Ever since I met Jacquie, I knew this was going to be a good thing. Instant connection, with one so knowledgeable, professional, personable, and attentive.
- Rhonda Everett
Eva and Jacquie have been absolutely amazing in helping us navigate private insurance as well as Medicare and supplements. They are both readily available for consultation whenever we have reached out.
- Sue Varrasi